Investment Opportunities

Preferred Stock in an Established Equipment Finance Business 

Blue Bridge's Series D and Series E preferred stock offerings provide accredited investors with an equity interest in Blue Bridge Financial, Inc., a privately held equipment finance company. Explore the operating business, compare offering terms, and understand the investment's risks and liquidity considerations below.

The Business Behind the Investment

The investment thesis is grounded in Blue Bridge's ability to manage the equipment finance lifecycle through a fully integrated operating platform spanning origination, underwriting, funding, servicing, and recovery.

2009

Founded

$800M+

Loans originated since inception1

9,000+

Businesses funded since inception1

7,000+

Serviced transactions since 20141

1 Company-provided information as of December 31, 2025

Revenue is generated through four primary channels: interest income, loan sale gains, servicing fees, and origination fees.

Explore Series D & Series E

Compare offering terms, dividend provisions, redemption features, and key investment considerations. Important Risk Disclosures.

Liquidity Disclosure

The initial term is not a guaranteed redemption date. Redemption is subject to timely notice, available cash, debt covenants, governing documents, and Board discretion. The stated dividend is not guaranteed and should not be presented as realized yield.

OFFERING TERMS2
Term Series D Series E
Stated Annual Preferred Dividend Rate 12% 14%
Initial Term 18 Months 36 Months
Maximum Offering Up to $5 Million Up to $20 Million
Offering Price $100 Per Share $100 Per Share
Minimum Purchase $25,0003 $25,0003
Dividend Frequency Monthly, In Arrears Monthly, In Arrears
Redemption notice At least 90 days before maturity At least 90 days before maturity
If not redeemed Term extends 12 months Term extends 12 months

Offered under Rule 506(c) to verified accredited investors only. The Shares are unregistered, restricted, illiquid and speculative, and involve a high degree of risk, including loss of the entire investment; dividends and redemptions are not guaranteed. Offers are made only by the Private Placement Memorandum. See Disclosures.

Redemption requests must be received at least 90 days prior to the initial maturity or the Shares’ maturity date will be extended for twelve months from the initial maturity date. Requests received after the Redemption Request Deadline may be considered, and may be approved, at the sole discretion of the Company.

Dividends are not guaranteed and are dependent upon the successful operations of the Company. While the Company intends to pay investors dividends on a monthly basis, there can be no assurance that the Company will succeed in doing so.

Important Risk Disclosures.

2  Investment is speculative and involves a high degree of risk, including possible loss of investment. See PPM for more complete discussion of risks.
3 The Company reserves the right to waive or reduce the minimum investment amount.

MARKET CONTEXT
The Company's Origination Platform Operates Within a Large and Expanding Equipment Finance Ecosystem

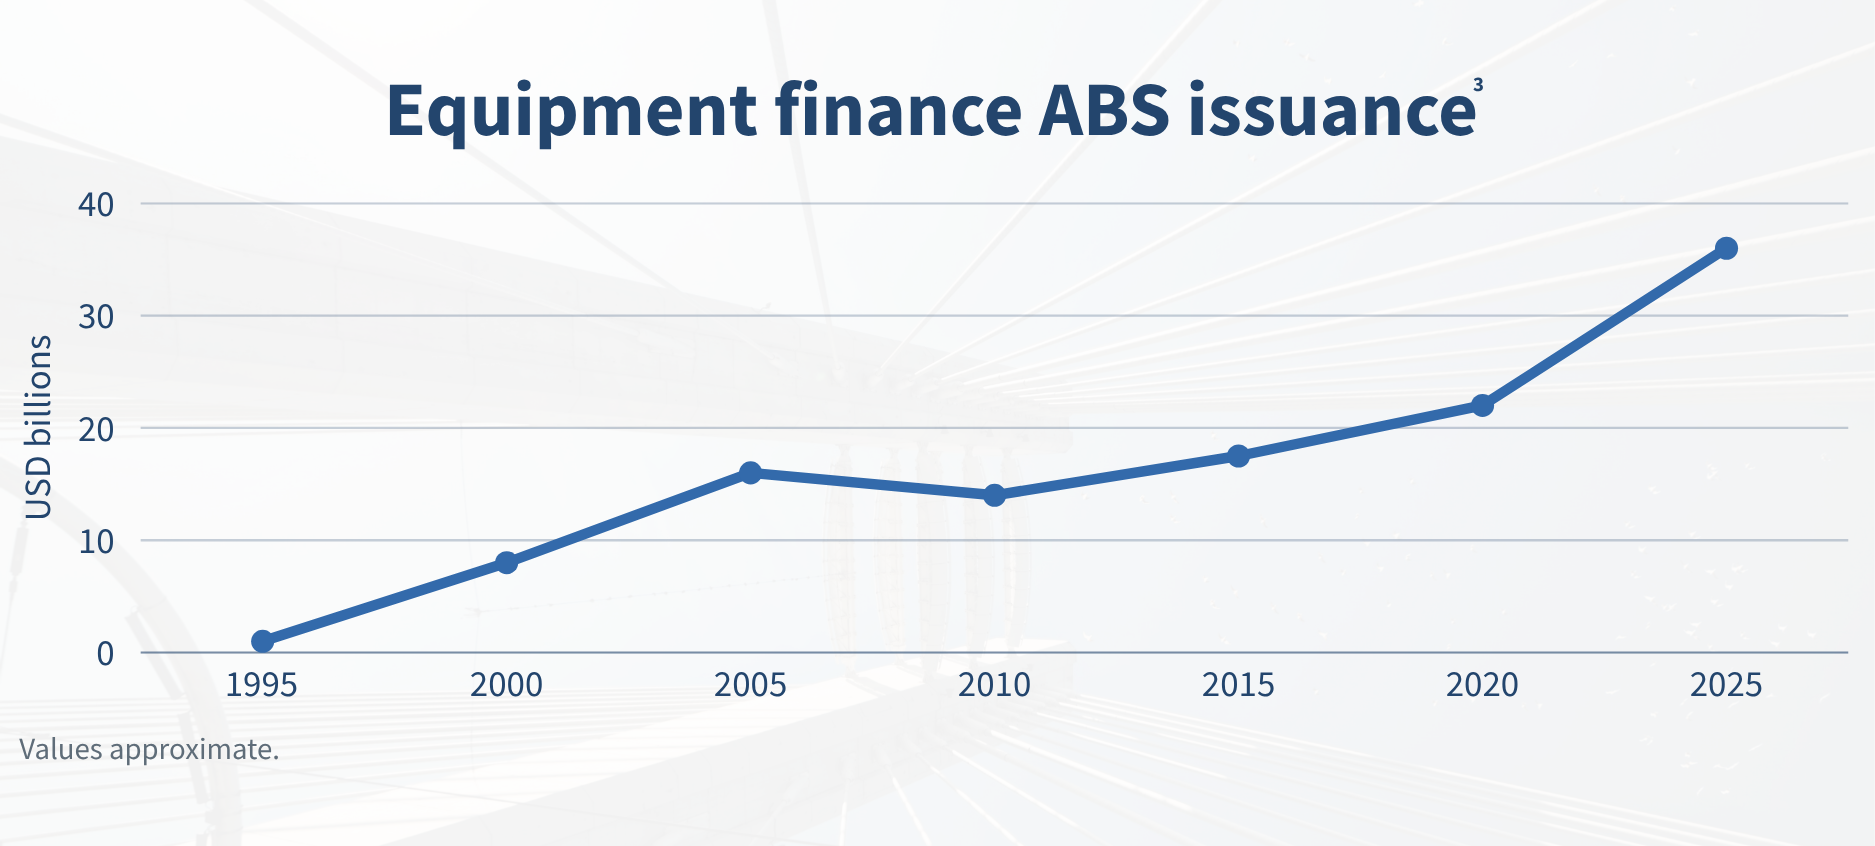
Industry growth, strong equipment demand, and expanding ABS issuance continue to support the broader equipment finance landscape.

$1.3T+

U.S. equipment finance market 4

+30%

YOY  small-ticket equipment financing new business growth 4
A Diversified Approach to Origination

Independent Originators

Third-party equipment finance professionals referring financing opportunities.

Direct Business Development

Existing client relationships, proprietary databases, referrals, and digital marketing.

Vendor Programs

Partnerships that present financing at the point of equipment sale.

Integrated Oversight Across the Loan Life Cycle

Blue Bridge manages every stage of the equipment finance lifecycle through an integrated platform spanning sourcing, underwriting, funding, servicing, and asset recovery.

Origination
Source equipment financing requests. 

Credit Review
Evaluate the borrower, equipment, and proposed terms.

Funding
Complete documentation and fund approved transactions.

Servicing
Process payments and monitor loan performance. 

Collections
Proactive portfolio monitoring and account resolution.

Recovery
Manage collection and recovery efforts when needed.

Managing these functions within one platform supports continuity of information, coordinated decision making, and ongoing oversight throughout the loan life cycle.

How the Business Generates Revenue

Blue Bridge generates revenue by originating, financing, selling, and servicing equipment loans. Its integrated platform supports four primary revenue sources. 

Interest Income

Interest earned on loans held by the company.

Origination Fees

Fees earned in connection with originating equipment financing transactions.

Loan Sale Gains

Gains that may be realized when originated loans are sold to institutional purchasers.

Servicing Fees

Fees earned for administering loans on behalf of loan owners.

Revenue from these activities supports the company's operations. Financing costs, credit losses, and operating expenses affect profitability and cash availability.
01

Expand Lending Capacity

Equity capital works alongside financing facilities to support loan originations. These facilities expand funding capacity while introducing financing costs, repayment obligations, and covenant requirements.

02

Retain or Sell Loans

Blue Bridge may retain loans to earn interest income or sell selected loans to institutional purchasers. Loan sales may generate gains and release capital for additional lending, subject to pricing and financing arrangements.

03

Continue Servicing

When Blue Bridge retains servicing responsibilities on sold loans, it can continue administering payments and managing accounts while earning servicing fees.

In addition to investor capital and financing partnerships, principal repayments from borrowers and proceeds from selective loan sales may generate liquidity that can be redeployed into new lending opportunities.
$165M
Total consolidated assets
$155M
In financing facilities
~$50M
In loans sold to institutional purchasers in FY2025
This capital recycling can enhance platform capacity and support continued portfolio growth.

1 Company-provided information as of December 31, 2025

Credit Discipline Across the Loan Life Cycle

Blue Bridge’s credit process is guided by a board-adopted loan policy, a proprietary scorecard, and a tiered credit matrix. These standards support lending decisions, while integrated servicing, collections, and recovery extend oversight beyond initial underwriting.

01

Submit

Application from originator, vendor, or Blue Bridge direct sales.

02

Screen

Restricted industry and equipment lists, OFAC screening, identity verification.

03

Score

Proprietary model; risk-based pricing; up to 40 predictive attributes.

04

Verify

Bureaus, business credit, public records, bank data, and site inspection.

05

Decide

Credit manager review with escalated exception handling.

06

Document

E-signature, multi-factor authentication, and electronic documentation.

07

Fund

Verbal confirmation, UCC filing, and same-day funding availability.

Blue Bridge combines proprietary credit modeling, structured review processes, and ongoing portfolio oversight throughout the equipment finance lifecycle.

How Loans Are Structured

Business-essential equipment
U.S.-based collateral
Monthly principal and interest payments
ACH payment requirements
Personal guarantees on 97% transactions1
Industry restrictions and collateral review
Investor Relations

Interested in Our Investment Strategy?

Learn how Blue Bridge sources, underwrites, and services equipment-secured loans through its credit process.

EQUIPMENT-SECURED LOANS • IN-HOUSE UNDERWRITING • LOAN SERVICING
Contact Investor Relations →

Investors purchase preferred stock of Blue Bridge Financial, Inc. and do not own, or hold a security interest in, the Company’s loans or equipment. There can be no assurance the underlying collateral will be sufficient to provide returns, including the preferred returns to investors.

1 Company provided as of 12/31/25. Guarantees may not result in full or timely recovery

How Oversight Continues After Funding

Our involvement extends beyond origination. Dedicated servicing, active portfolio monitoring, and established recovery procedures help support portfolio performance throughout the life of each loan.

Servicing & Monitoring

Process payments, monitor account activity, and maintain borrower communication throughout the repayment period. 

Collections & Resolution

Use staged outreach and account-resolution efforts to address missed payments and other servicing issues. 

Recovery & Remarketing

When necessary, pursue recovery through the business, equipment collateral, and applicable personal guarantees. Equipment recovery may include repossession and remarketing through vendor, auction, or retail channels. 

These practices support credit evaluation and loan oversight but do not eliminate losses. Recovery outcomes depend on borrower and guarantor resources, equipment value, market conditions, and applicable legal constraints.

Portfolio Profile & Operating History

Blue Bridge finances essential-use equipment for small businesses across multiple industries and U.S. states. The characteristics below provide a snapshot of the underlying lending platform and portfolio composition.

Portfolio Snapshot*

~$83K

Typical Loan Size 1

24-60 Months

Typical Term 1

709

Weighted Average FICO Score 2

8 Years

Average Years in Business 1

1 Company-provided information as of December 31, 2025
2 Company provided as of 12/31/25. Credit scores are one factor in underwriting and do not ensure loan performance

Portfolio exposure spans multiple industries and geographic markets, helping reduce reliance on any single borrower segment while maintaining focus on essential-use equipment financing.

Industry Diversification

  • Construction
  • Healthcare
  • Transportation
  • Manufacturing
  • Business Services
  • Food & Beverage
  • Other Commercial Industries

Geographic Reach

  • Multi-State Origination Platform
  • Broad Regional Representation
  • Diverse Local Economies
  • Established Small Business Borrowers
  • Nationwide Equipment Finance Relationships

Portfolio Disclosure

Portfolio exposure spans multiple industries and states, with concentrations that can affect performance. Diversification does not eliminate credit risk or the possibility of loss.

✓

Profitable Since 2018

Demonstrated operating profitability while continuing to expand portfolio originations and servicing capabilities.

Company provided as of 12/31/25. Past performance does not guarantee future results.

✓

Audited Financials Since 2009

Long-standing commitment to financial transparency supported by independently audited annual financial statements.

Company provided as of 12/31/25.

✓

Zero Covenant Violations

Consistent compliance with financing agreements and reporting requirements throughout operating history.

Company provided as of 12/31/25. Past compliance does not ensure future compliance.

Blue Bridge's underwriting, collateral and personal guarantees are designed to manage credit risk, but they do not eliminate it. The Company has experienced credit losses and delinquencies, and losses have varied over time and have increased in certain periods and industries. When credit trends deteriorate, the Company may tighten its credit criteria, as it has done in the past. Recoveries depend on collateral values, guarantor resources and legal processes, and may take an extended period. Future losses may be higher than historical levels. Historical loss and recovery information is included in the offering materials — contact Investor Relations to request the

*Portfolio characteristics as of December 31, 2025

Interested in Reviewing Current Investment Opportunities?

Contact Investor Relations to discuss portfolio characteristics, financial reporting, and the offering materials available for your review. 

Investment Considerations

An investment in Blue Bridge Financial, Inc.’s preferred stock is speculative, illiquid, and involves a high degree of risk, including the possible loss of your entire investment.

01 Ownership

Ownership in the Operating Company

Investors purchase restricted, non-voting preferred equity in Blue Bridge Financial, Inc. Preferred shareholders do not directly own loans or equipment collateral and are subject to the company's overall financial performance.

02 Dividends

Dividends Are Not Guaranteed

Preferred dividend rates are not guaranteed returns. Payment depends on available cash flow, debt covenants, governing documents, and Board discretion.

03 Liquidity

Limited Liquidity & Redemption

No public market exists for the shares. Redemption requests may be delayed, limited, or denied and investors may need to hold shares indefinitely.

04 Borrower Risk

Borrower & Collateral Risk

Borrowers may fail to repay their obligations. Equipment collateral and personal guarantees may not fully recover outstanding balances and collection costs.

05 Financing

Financing & Earnings Risk

Changes in financing availability, borrowing costs, loan sale markets, or covenant restrictions may adversely impact profitability and liquidity.

06 Operations

Operational & Execution Risk

Results depend on personnel, underwriting performance, technology systems, and successful execution of company strategy.

07 Eligibility

Offering Requirements

The offering is conducted under Rule 506(c) of Regulation D. Participation is limited to accredited investors who successfully complete verification requirements.

These are selected risks and not a complete list. Prospective investors should carefully review all offering documents, subscription materials, redemption provisions, and risk disclosures before making an investment decision.

Ready to Explore the Opportunity?

Learn more about Blue Bridge's investment platform, underwriting methodology, and current opportunities by connecting with our Investor Relations team.

Contact inquiry

Speak With Our Investor Relations Team

Step 1 of 2

I am a…